A water damage insurance claim in West Hollywood, CA starts the moment you notice the water, not the moment you file. A claim is your written request for your insurer to evaluate a loss under the terms of your policy, and what you do in the first day often shapes how smoothly it goes.
This guide is general information only. It does not tell you what your policy covers, and your own policy and your insurer have the final word.
How different losses are commonly treated
Sudden and accidental water damage, such as a pipe that bursts or an appliance hose that fails, is often covered. Gradual leaks, long-term seepage and damage from neglect often are not. Flood damage is usually excluded and needs separate flood coverage.
| Type of loss | Commonly treated | What to document |
|---|---|---|
| Burst pipe or failed supply line | Often covered when sudden and accidental | Photos of the failed part, the date, water spread |
| Slow leak behind a wall | Often not covered when gradual | Stain history, any earlier repair notes, moisture readings |
| Rain or surface flood | Usually excluded without flood coverage | Waterline photos, weather date, entry points |
| Sewage backup | Varies, may need an added endorsement | Photos, plumber report, items affected |
Always check your policy and ask your insurer how your specific loss is treated.
Take reasonable steps to stop more damage
The California Department of Insurance advises making temporary repairs to prevent further damage. Its claims guide warns that a policy may not cover ensuing damage if you have not taken reasonable steps, so stopping the source and starting extraction early protects the claim as well as the building.
Turn off the water, move belongings out of the wet area and call a crew to remove standing water. Our water damage cleanup page lists what that first stage includes, and a crew can give you a written scope to share with your insurer.
Keep a log and keep copies
The same state guide tells policyholders to keep a log of all phone calls and correspondence, and to make copies of anything sent or received. A simple notebook or note on your phone works. Record the date, the person and what was said.
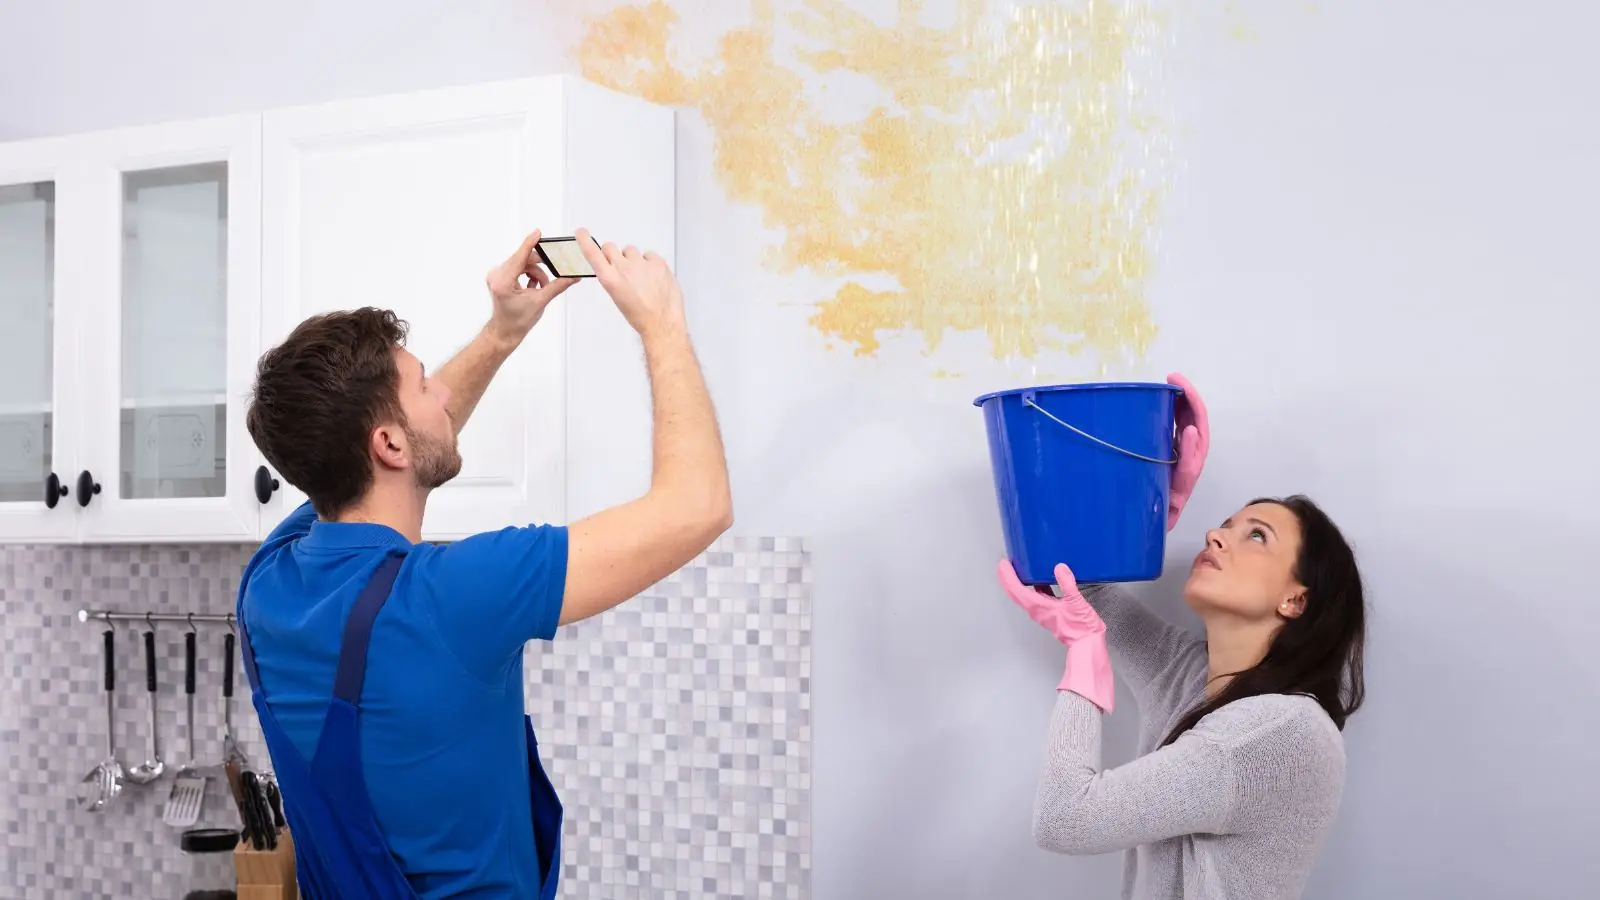
- Dated photographs and video before anything is moved or thrown away.
- A room-by-room list of damaged items with rough age and where each was kept.
- Receipts for emergency costs such as extraction, lodging or disposal.
- The written scope of work and moisture readings from the drying crew.
- Copies of every message to and from your insurer.
Water damage and a claim to start?
Call the 24/7 line. A crew can stop the spread and write down what was wet so you have clear records.
Flood coverage is a separate question
The California Department of Insurance says homeowners and commercial policies typically exclude flood, mudslide and debris flow. Flood policies are sold through insurance agents and some private insurers, usually through the National Flood Insurance Program, and a standard policy generally takes effect 30 days after purchase.
That waiting period is why flood coverage cannot be arranged after water is already at the door. If your property borders Beverly Hills or you are comparing coverage, read the policy language before you need it, and see our flood damage restoration page for what that work involves.
Repair work after the claim decision
Ask your insurer whether it needs to inspect the damage before permanent repairs begin. Once it does, rebuilding drywall, flooring and paint follows the drying stage, and our water damage repair page explains the order. Hold off on discarding materials your insurer may want to see unless they are unsafe to keep.
Questions worth asking your insurer
A short call list keeps the conversation focused. Write the answers in your log with the date, because details matter later and memory fades quickly during a stressful week.
- Is my loss treated as sudden and accidental, or as gradual?
- Does my policy cover the cost of stopping and drying the damage, not only the rebuild?
- Do I need to keep damaged materials until an inspection happens?
- What paperwork do you need from the crew that dried the property?
- Is there a separate deductible or limit that applies to this kind of loss?
Insurers differ and so do policies, which is why the same burst pipe can be handled differently from one household to the next. If you disagree with a decision, the state guide explains how to ask for a review and points to the Department of Insurance for help.
Condo owners, landlords and neighbors
Many buildings in the area share walls, floors and plumbing, so a loss may involve an association policy, a landlord policy and your own policy at once. Ask your association or property manager which policy responds first and who is hiring the drying crew.
The same questions apply to properties across the western edge of town in Beverly Hills, where building rules and utilities differ from those in West Hollywood. Confirm which city and which utility apply before you place any calls.
Flood insurance in West Hollywood today
The City of West Hollywood reports it received a Letter of Map Revision from FEMA after two decades of storm drain construction by the County of Los Angeles. The city states that there are no longer any parcels in West Hollywood that must carry mandatory flood insurance, and about 400 properties in the southwest part of the city had been required to before the revision.
Optional is not the same as covered. A property owner no longer required to carry flood insurance may still have no coverage for flood damage unless a separate policy is in place, so it is worth asking your insurer or agent what your building actually has. The state also publishes Fair Claims Settlement Practices Regulations that set deadlines for insurers to acknowledge and evaluate claims, available at insurance.ca.gov.
Sources: City of West Hollywood Flood Insurance Map Revision page, California Department of Insurance Residential Claims Guide and flood facts page
Common questions from West Hollywood readers
Should I call my insurer or a restoration crew first?
If water is spreading, stop the source and call a crew right away, then notify your insurer promptly. The state guide advises taking reasonable steps to prevent further damage.
Is every water leak covered?
No. Sudden and accidental damage is often covered, while gradual leaks and neglect often are not. Check your policy and ask your insurer about your specific loss.
Do I need flood insurance in West Hollywood?
The city says no parcel is now required to carry it, but optional is not the same as covered. Ask your insurer or agent whether your property has any flood protection.
How long do insurers have to respond to a claim?
State regulations set deadlines for insurers to acknowledge and evaluate claims. The California Department of Insurance publishes them at insurance.ca.gov.
What if my loss came from a street pipe near my West Hollywood building?
Ask your insurer how it treats the loss and ask the utility about its own claims process. Keep photos, receipts and your call log for both.